
The $40 Trillion Warning and Reason to Worry

 Amazon Music

 Apple Podcasts

 Spotify

 iHeartRadio

 Youtube Music

 TuneIn

 Castro

 Audible

 RSS Feed
The core takeaway is simple: debt becomes dangerous not because it reaches one symbolic number, but because deficits keep compounding faster than a country’s ability and willingness to finance them.
Supporting links
1. Federal Debt, $40 Trillion [CNBC]
2. U.S. Debt Clock [US Debt Clock website]
3. How Taxes and Tax Cuts Affect the U.S. Economy and Society [Letters &
Science]
Contact That's Life, I Swear
- Visit my website: https://www.thatslifeiswear.com
- Twitter at @RedPhantom
- Bluesky at @rickbarron.bsky.social
- Email us at https://www.thatslifeiswear.com/contact/
Episode Review
- Submit on Apple Podcast
- Submit on That's Life, I Swear website
Other topics?
- Do you have topics of interest you'd like to hear for future podcasts? Please email us
Interviews
- Contact me here https://www.thatslifeiswear.com/contact/, if you wish to be a guest for a interview on a topic of interest
Listen to podcast audios
- Apple https://apple.co/3MAFxhb
- Spotify https://spoti.fi/3xCzww4
- My Website: https://bit.ly/39CE9MB
Other
- Music and/or Sound Effects are cour...
⏱️ 11 min read
Hi everyone, and welcome to my podcast, That’s Life, I Swear. I’m your host, Rick Barron
Wednesday, August 20, 2026. Remember that date. Why, you may ask?
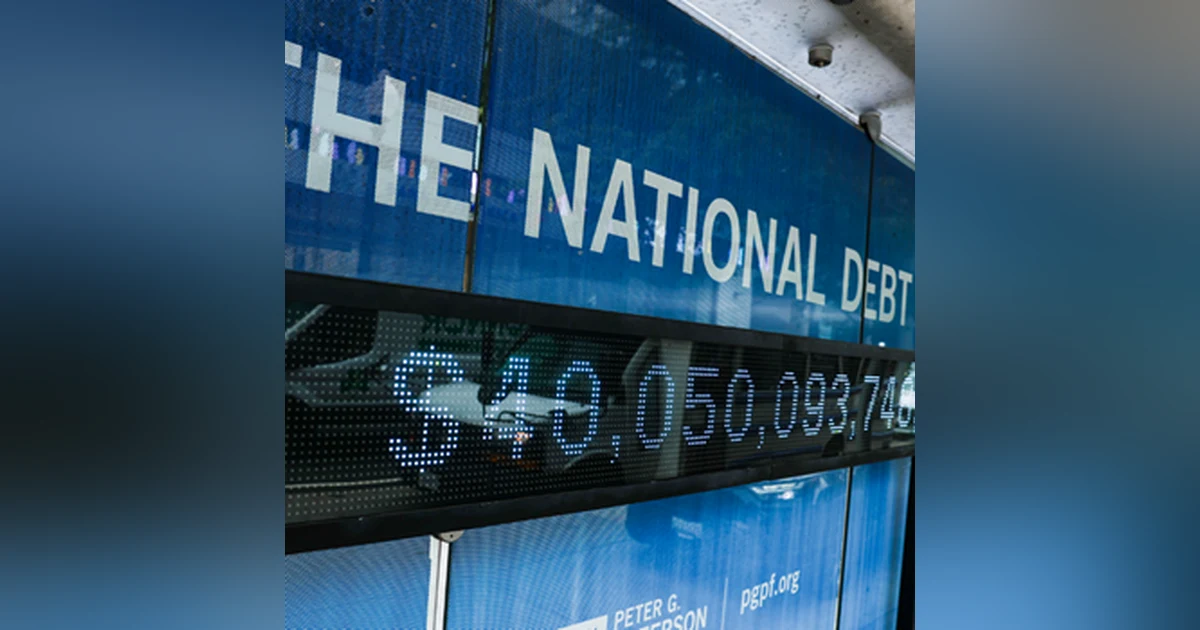
On that date, America’s national debt crossed a line so large it risks becoming abstract: $40 trillion dollars.
But the number is not merely a scoreboard of past borrowing—it is a warning about future choices.
Each year Washington spends more than it collects, it adds to a balance that must be refinanced, serviced, and ultimately carried by the same economy that younger Americans will inherit. Should we worry? Hell yes.
Welcome to That's Life, I Swear. This podcast is about life's happenings in this world that conjure up such words as intriguing, frightening, life-changing, inspiring, and more. I'm Rick Barron your host.
That said, here's the rest of this story
America’s $40 Trillion Tab Is No Longer a Distant Problem
The United States has moved past another fiscal landmark, with total federal debt exceeding $40 trillion. Treasury data put total public debt outstanding at roughly $40.047 trillion after it crossed the threshold this week. That total includes debt held by outside investors as well as money the government owes to its own accounts, such as Social Security trust funds.
The headline figure is staggering, but it needs context. A country’s debt is not judged the same way a household’s credit-card balance is judged. The United States has a vast economy, a taxing authority, and the ability to borrow in its own currency. The more revealing question is whether the debt is growing faster than the nation’s capacity to pay for it.
On that test, the nation is moving in the wrong direction.
Economists focus closely on debt held by the public—Treasury securities owned by investors, banks, pension funds, mutual funds, foreign buyers, and other market participants. That measure is already above $32 trillion. It is also near the size of the entire U.S. economy over a year, an unusually high level outside periods of national emergency.
The Congressional Budget Office projects that debt held by the public will equal 101% of gross domestic product in 2026, rise to 120% by 2036, and reach 175% over the subsequent two decades if current-law trends continue.
In plain terms: America is increasingly borrowing amounts that are large relative to the income-generating capacity of the economy that must support them.
How the balance sheet unraveled
The United States was not always on this path. At the start of the 2000s, publicly held debt was comparatively low after several years of federal budget surpluses. Then came a series of expensive shocks and policy decisions that steadily changed the nation’s financial position.
The early 2000s brought
1. tax reductions
2. the aftermath of the dot-com bust
3. and wars that increased federal spending
4. The 2007–09 financial crisis then cut tax revenue while pushing Washington to spend more on economic rescue efforts and unemployment support
5. The COVID-19 pandemic dramatically accelerated borrowing again as the government financed emergency checks, business assistance, health measures, and other relief programs
Those events explain much of the rise. But they do not fully explain why deficits remain so large after the emergencies passed.
America now faces a structural gap between what it promises to spend and what it regularly collects in revenue. An aging population is increasing the cost of Social Security and Medicare. Health-care costs remain significant. Interest costs rise as the government rolls over old debt and issues new bonds at higher rates. Meanwhile, federal revenue has not expanded enough to consistently cover those obligations, especially when policymakers extend or enact tax cuts without equivalent spending reductions.
The result is a recurring deficit: the government spends more in a year than it receives. Each annual shortfall is added to the national debt.
Why cutting the debt is politically difficult
The federal budget leaves less room to maneuver than many people assume.
A large share of spending goes to programs that provide benefits directly to people—especially Social Security, Medicare, Medicaid, and other health-related programs. These are not obscure line items. They affect retirees, disabled Americans, families, doctors, hospitals, and communities across the country. Any effort to slow their growth can bring immediate political consequences.
Then there is interest on the debt. The government cannot simply choose not to make those payments without risking a default and a global financial shock. Annual interest costs have now moved above $1 trillion and have become the federal government’s second-largest expense, behind Social Security.
That leaves a smaller portion of the budget for everything else: defense, transportation, research, education, disaster response, veterans’ services, law enforcement, national parks, federal payrolls, and the day-to-day machinery of government.
This is the trap. Elected officials can avoid the pain of reform in the short run by borrowing more. But every delay makes future correction harder because the debt itself produces a growing interest bill. The government gradually devotes more money to paying for yesterday’s decisions and has less flexibility to invest in tomorrow’s needs.
The danger is not necessarily a sudden collapse
The risk is often misunderstood. A $40 trillion debt does not mean the United States will wake up tomorrow unable to function. Treasury bonds remain central to global finance because investors generally view them as liquid, dependable assets that can be bought and sold easily. That special status gives the U.S. far more borrowing capacity than most countries possess.
As Treasury issues more debt, it must continue finding buyers. If investors begin demanding higher yields to compensate for larger deficits, inflation concerns, political dysfunction, or uncertainty over the government’s fiscal direction, borrowing becomes more expensive. Higher Treasury yields can ripple through the economy, influencing mortgage rates, auto loans, business financing, credit-card rates, and the cost of capital for employers.
That creates a damaging feedback loop:
- Large deficits require more borrowing
- More borrowing can push interest costs higher
- Higher interest costs widen future deficits
- Wider deficits require still more borrowing
The issue young Americans inherit
Young workers may face an economy in which more tax dollars go to interest payments rather than infrastructure, schools, scientific research, housing initiatives, climate resilience, or programs that improve long-term productivity. They may also confront pressure for future tax increases, slower benefit growth, later retirement ages, or some combination of all three.
The lesson is not that government borrowing is always irresponsible. Borrowing can be essential during a war, recession, disaster, or national emergency. Businesses borrow to build factories; families borrow to purchase homes; governments may borrow to prevent economic collapse or finance investments with long-term benefits.
The distinction is whether the borrowed money is used wisely and whether there is a credible plan to pay for permanent commitments. Borrowing for an emergency can be necessary. Borrowing indefinitely to avoid difficult choices is something else entirely.
The country’s $40 trillion milestone should force a basic question: What does America want its future budget to accomplish—and what is it willing to pay for?
What can we learn from this story? What's the takeaway?
The core takeaway is simple: debt becomes dangerous not because it reaches one symbolic number, but because deficits keep compounding faster than a country’s ability and willingness to finance them.
For the public—and especially younger Americans—the lesson is one of accountability:
- A budget cannot rely forever on borrowing to cover routine expenses.
- Ignoring a recurring shortfall makes future solutions more painful.
- Tough reforms are easier when made early and gradually than when forced by a market shock.
- Economic strength matters, but growth alone may not overcome persistent deficits and rapidly rising interest costs.
- A responsible solution will probably require trade-offs on both spending and taxes, rather than pretending one side of the ledger can solve the problem alone.
Well, there you go, my friends; that's life, I swear
For further information regarding the material covered in this episode, I invite you to visit my website, which can be found on Apple Podcasts, for show notes and the episode transcript.
As always, I thank you for the privilege of you listening and your interest.
Be sure to subscribe here or wherever you listen to podcasts so you don't miss an episode.
See you soon.


